Mortgage rate changes happen all the time. Sometimes it’s a full percentage point over a period of time, and sometimes we’re talking about a change of just .10%.
But what do those numbers actually mean to a buyer’s monthly budget?
Let’s put some real numbers to it using the Austin-area housing market. We’ll use a $435,000 home, roughly where the Austin-area median home price has been hovering, with 20% down and a 30-year fixed-rate mortgage.
That gives us:
Purchase price: $435,000
Down payment: $87,000
Loan amount: $348,000
Property taxes: $6,000 per year, or $500 per month
Homeowners insurance: $1,000 per year, or about $83 per month (these numbers will vary)
For simplicity, I’m leaving out HOA fees since those can vary considerably.
What Does a 1% Mortgage Rate Change Mean?
Let’s compare a 6% mortgage rate to a 7% rate on the same house. At 6%, principal and interest would be approximately $2,086 per month. At 7%, principal and interest would be approximately $2,315 per month.
That’s a difference of about $229 per month.
Once we add our estimated property taxes and homeowners insurance, we’re looking at approximately:
6% rate: $2,670 per month
7% rate: $2,899 per month
Same house. Same down payment. Roughly $229 more in the monthly housing budget based solely on the interest rate.
That’s a meaningful difference when you’re looking at affordability.
What About a .10% Change?
Let’s look at a move from 6.5% to 6.6%. On our $348,000 loan, principal and interest increases from approximately $2,200 to $2,223 per month.
That’s about $23 more per month.
Add our estimated property taxes and homeowners insurance, and the monthly housing expense goes from approximately $2,783 to $2,806.
Twenty-three dollars by itself may not seem like a lot.
If rates continue moving up, those smaller increases start stacking up:
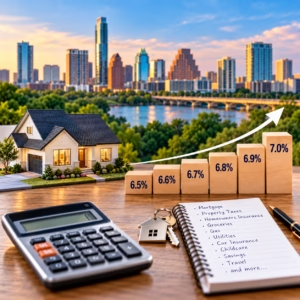
- 6.5%: about $2,200 per month in principal and interest
- 6.6%: about $2,223 — roughly $23 more
- 6.7%: about $2,246 — roughly $46 more
- 6.8%: about $2,269 — roughly $69 more
- 6.9%: about $2,292 — roughly $92 more
- 7.0%: about $2,315 — roughly $116 more
So while a single .10% move may not seem significant, a half-point move from 6.5% to 7% adds approximately $116 per month to the mortgage payment on this house.
Why Small Mortgage Rate Changes Add Up
But a household budget doesn’t exist in a vacuum.
The mortgage payment is coming out of the same budget as groceries, gas, electricity, car insurance, health insurance, childcare and everything else that has become more expensive.
Another $23 here, $40 there and $75 somewhere else starts to add up.
A few .10% increases can turn into a much more noticeable change in the monthly payment.
That’s why buyers watch even relatively small movements in mortgage rates. It’s not necessarily because a .10% increase suddenly makes a house unaffordable. It’s because housing is one piece of the overall household budget, and buyers are looking at how all of those expenses fit together every month.
When Interest Rates Rise, Home Prices Feel the Pressure
As rates go up, the monthly payment on the same house goes up. That means some buyers can no longer afford—or simply aren’t willing to pay—the same price they would have when rates were lower.
Go back to our $435,000 example with a 1% difference. Nothing about the house changed. The kitchen didn’t get bigger. The location didn’t get better. The buyer is simply being asked to spend about $229 more every month to own the exact same house.
At some point, buyers adjust.
They may lower the price range they’re searching in. They may decide not to buy at all. Or they may look at a house and decide that the price no longer makes sense for the payment.
When enough buyers make those same decisions, demand at a particular price point starts to soften. Homes can take longer to sell, sellers may have to negotiate more, and prices can come under downward pressure.
That’s part of the relationship between interest rates and home prices.
Higher rates tend to put downward pressure on prices because they reduce what buyers can comfortably spend each month. Lower rates can do the opposite by giving buyers more purchasing power.
And in a market like Austin, where buyers currently have choices, the monthly payment can have a very real influence on what buyers are willing to pay for a house.